Property Damage Litigation in South Florida
Property Severely Damaged? Make Sure Your Insurance Company Pays What It Should.
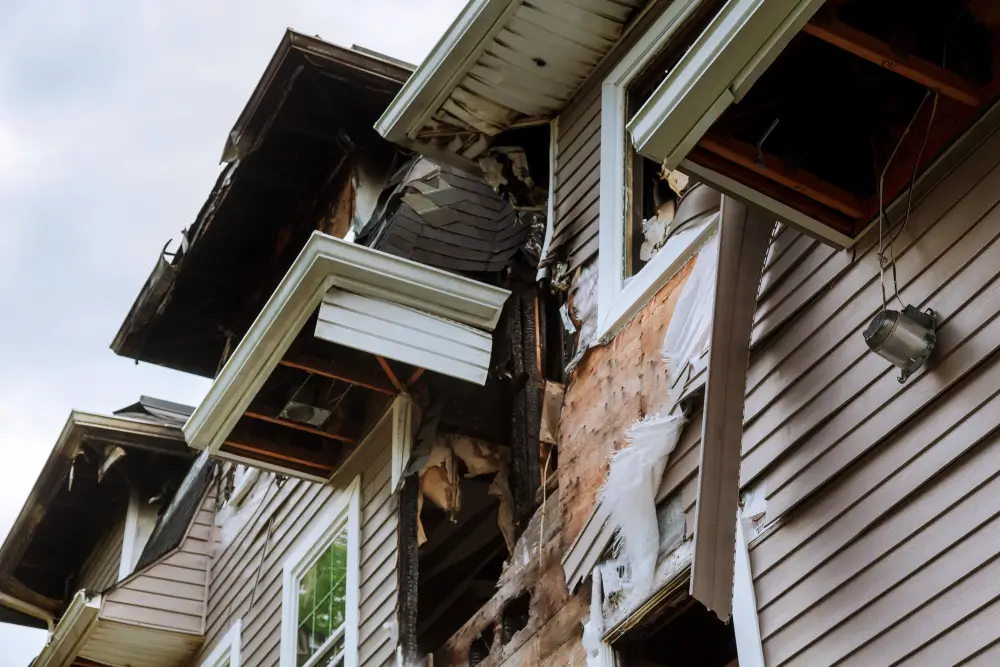
Your property is one of your most significant investments. When it suffers serious damage, you expect your insurance company to honor the coverage you paid for. Unfortunately, insurance companies may delay claims, deny coverage, undervalue damage, or offer far less than what is necessary to properly repair or restore the property.
Whether you are dealing with hurricane damage, a major plumbing or water loss, fire damage, or contractor negligence, Attorney Alan Blose provides strategic civil litigation focused on protecting your rights, challenging inadequate damage assessments and insurance claim decisions, and pursuing the full compensation you are entitled to recover.
Schedule Your Legal Strategy Session
The Challenging Landscape of Florida Property Claims
How Insurance Companies Can Undervalue Property Damage Claims
Don't Assume the Insurance Company's Initial Decision Is the Final Word
Florida’s property insurance landscape has become increasingly difficult for property owners. When an insurance company sends an adjuster to evaluate your loss, that adjuster is working on behalf of the insurance company—not you. Disputes can arise over the cause and extent of the damage, whether damage resulted from pre-existing wear and tear, the scope and cost of necessary repairs, and whether particular losses are covered under the policy. Claims may also face lengthy investigations or initial payment estimates that fall well short of the actual cost of restoring the property.
Accepting an inadequate initial payment or attempting to navigate complex policy exclusions without legal guidance can leave property owners without the additional funds necessary to fully repair or restore a home or commercial property.
1
Evaluate the Damage and the Claim
We review the property damage, the insurance company’s assessment, repair estimates, photographs, reports, and other available documentation. When appropriate, we work with qualified professionals—including public adjusters, contractors, engineers, and other experts—to evaluate the full scope and cause of the loss.
2
Review Your
Insurance Coverage
We carefully review the insurance policy, including applicable coverage, exclusions, endorsements, deductibles, and policy limits, to determine what coverage may be available and identify the issues affecting your claim.
3
Challenge an Improper Denial or Underpayment
If an insurance company denies a covered claim, undervalues the damage, delays payment, or otherwise fails to properly handle the claim, we challenge that decision and pursue the additional benefits available under the policy and Florida law.
4
Litigation When Necessary
When a property insurance dispute cannot be resolved, Attorney Alan Blose is prepared to file suit and litigate the claim. The goal is straightforward: hold the insurance company to its obligations and pursue the compensation necessary to repair or restore your property.
Relentless Civil Advocacy
Fighting for the Coverage
You Paid For
You paid your premiums and upheld your end of the insurance contract. When your property suffers a covered loss, you should be able to expect your insurance company to do the same.
When an insurance company denies a claim, delays payment, or undervalues the extent of the damage, property owners can find themselves facing a complicated and frustrating process at the very time they need their coverage most. Our Fort Lauderdale civil litigation team takes that burden on for our clients.
We work closely with experienced public adjusters, contractors, engineers, and other qualified experts to thoroughly document the damage, determine the scope and cost of necessary repairs, and develop the evidence needed to support the claim. When the insurance company’s assessment does not reflect the true extent of the loss, we are prepared to challenge it.
Alan Blose brings more than a decade of legal experience to representing homeowners and commercial property owners in property damage claims and litigation throughout Broward, Miami-Dade, and Palm Beach Counties.

What Drives Us
AMB Law Satisfied Clients Are Saying
Why Choose AMB Legal for Your Property Damage Lawsuit?
1
Experienced Civil Litigation
Property damage claims do not always end with the insurance company’s initial decision. When a dispute requires litigation, Alan Blose brings more than a decade of legal experience to advocating for property owners and pursuing the recovery available under their policies and Florida law.
2
A Team Focused on Your Case
Property damage cases often require input from multiple professionals. Our attorneys and legal team work together with public adjusters, engineers, contractors, and other qualified experts when appropriate to develop and support each client’s claim.
3
Thorough Policy and Coverage Analysis
The terms of an insurance policy can significantly affect what is covered and how much may be recoverable after a loss. We analyze the policy, endorsements, exclusions, deductibles, coverage limits, and other applicable provisions to identify available coverage and address disputes raised by the insurance company.
4
Building the Evidence to Support Your Recovery
A successful property damage claim requires more than simply showing that damage occurred. We work to establish the cause and extent of the loss, the repairs necessary to restore the property, and the reasonable cost of those repairs. When another person or entity may also be responsible for the damage, we evaluate those potential sources of recovery as well.
Many property owners believe that continuing to call their insurance adjuster or repeatedly challenging the insurance company’s decision on their own will eventually resolve the problem. But once an insurance company has denied a claim, significantly undervalued the damage, or failed to properly address a loss, simply continuing the same back-and-forth may not be enough.
Retaining an experienced property damage attorney early can change the course of the claim. With the right legal strategy and the support of qualified experts, you can directly challenge the insurance company’s assessment, document the true extent of your loss, and pursue the coverage and compensation available under your policy
Property Damage Attorney
Frequently Asked Questions:
Florida Propert Damage Defense
What should I do if my property insurance claim is completely denied?
A denial does not necessarily mean the end of your claim. If your insurance company denies coverage, carefully review the written denial and the policy provisions or exclusions the company relies upon in reaching its decision. Then, contact an experienced property damage attorney to evaluate whether the denial is supported by the terms of your policy and the facts surrounding the loss.
Our firm will review your policy, the insurance company’s stated basis for denial, and the available evidence concerning the damage. When appropriate, we work with qualified experts to further evaluate the loss, challenge an improper denial, and pursue litigation when necessary to seek the coverage available under your policy.
Can I still pursue a lawsuit if the insurance company already paid me, but the check is too low?
Yes. Receiving a payment from your insurance company does not necessarily mean that you have accepted the amount as full and final resolution of your claim. If the insurance company undervalued the damage, underestimated the scope or cost of necessary repairs, or otherwise failed to pay the full amount available under your policy, you may still be able to pursue additional payment.
Our firm can review the insurance company’s estimate, your policy, and the actual extent and cost of the damage to determine whether additional benefits may be owed. When necessary, we work with qualified experts to document the loss, challenge the insurance company’s assessment, and pursue litigation to recover the additional amount available under the policy.
What constitutes "bad faith" by an insurance company under Florida law?
Under Florida law, an insurance company may act in bad faith when it fails to attempt in good faith to resolve a claim when, under all the circumstances, it could and should have done so had it acted fairly and honestly toward its policyholder and with due regard for the policyholder’s interests.
Florida law also identifies a number of unfair claim settlement practices, including misrepresenting pertinent facts or policy provisions, failing to promptly acknowledge and act upon claim communications, and denying claims without conducting a reasonable investigation based on the available information.
Not every disagreement, delay, underpayment, or denial constitutes bad faith. Whether an insurance company’s handling of a property claim gives rise to a bad-faith claim depends on the particular facts and circumstances and the requirements of Florida law.
What is a supplemental claim, and what is the deadline to file one in Florida?
A supplemental claim seeks additional payment for loss or damage arising from the same event that was previously reported to and adjusted by the insurance company. This may occur when the insurance company’s original estimate did not account for the full scope of the damage, additional damage is identified, or the actual cost of completing covered repairs exceeds what was initially anticipated.
Under current Florida law, notice of a supplemental property insurance claim generally must be provided to the insurance company within 18 months after the date of loss. Because missing this deadline can prevent recovery of additional insurance benefits, property owners should have a potentially underpaid claim evaluated as soon as possible.
If my property is damaged by a third-party contractor's negligence, who may be responsible?
If a contractor, plumber, roofer, or other third party causes damage to your home or commercial property through negligent or defective work, you may have a claim against the contractor, company, or other parties responsible for the damage. Depending on the circumstances, applicable liability insurance may also provide coverage for the loss.
Our firm investigates how the damage occurred, identifies the parties who may be legally responsible, evaluates available insurance coverage, and works with qualified experts when necessary to establish the cause and extent of the damage. We then pursue the appropriate claims to recover the cost of repairing the property and other damages available under Florida law.
How Do I Schedule A Consultation?
Scheduling a consultation with AMB Law is easy. Simply give us a call at (954) 960 – 4413 to speak with our friendly staff and arrange a convenient time for you -or- schedule an online consultation.
We Are Here To Listen and Act.
We understand the fear, isolation, and uncertainty you are feeling right now. But you do not have to face the Florida justice system alone. Your consultation with AMB Legal is completely confidential and free of judgment. Speak directly with Elena and Alan, tell us exactly what happened, and let us show you how we are going to protect your future.
Call NOW (954) 960-4413